PepsiCo shares rebound after Q3 beat despite profit outlook cut
The rally followed Wednesday’s decline, when the stock touched an intraday low of $123.47 before closing at $123.73. Thursday’s rebound recovered the previous session’s losses, providing some relief to shareholders after the recent selloff.
The results, however, painted a mixed picture. PepsiCo delivered stronger sales but lowered its full-year earnings growth forecast as its North American recovery continued to take longer than management expected.
Revenue and adjusted earnings beat expectations
Third-quarter net revenue increased 5.6% year over year to $25.27 billion, while core earnings per share—PepsiCo’s adjusted earnings measure—reached $2.34. Both figures exceeded expectations.
Reported operating profit rose 19% to $4.26 billion. GAAP diluted earnings per share increased 17% to $2.23 from $1.90 a year earlier.
The distinction between reported and adjusted results is important. Reported profit growth substantially outpaced growth in PepsiCo’s core measures, indicating that the improvement in underlying profitability was more modest than the headline figures suggested.
North American sales show continued weakness
PepsiCo Foods North America reported broadly flat revenue. The North American beverages business posted 5% revenue growth, driven primarily by acquisitions. Organic revenue declined slightly in both businesses, according to management.
PepsiCo’s challenge is to rebuild demand while absorbing the costs of affordability initiatives, innovation and brand investment. North America remains a central test of the company’s recovery, with those efforts yet to deliver consistent organic growth and healthier margins.
Earnings outlook cut despite stronger sales expectations
PepsiCo now expects fiscal 2026 core EPS growth of 2.5% to 3.5%, down from its previous forecast at the low end of a 5% to 7% range.
The sales outlook was firmer. The company now expects net revenue growth of approximately 6%, at the upper end of its earlier 4% to 6% range.
The divergence captures the quarter’s central message: revenue growth is proving more resilient than earnings growth. Stronger sales have yet to fully offset the pressures on profitability.
PEP technical outlook: Rebound gains traction, but downtrend persists
Despite Thursday’s rally, PepsiCo shares remained down 18.51% over six months and 10.39% year-to-date as of the October 8 close.
The bounce from $123.47 is encouraging, but it has yet to signal a reversal of the broader bearish trend. Potential capitulation volume and a bullish engulfing candle provide the strongest technical support for a recovery attempt.
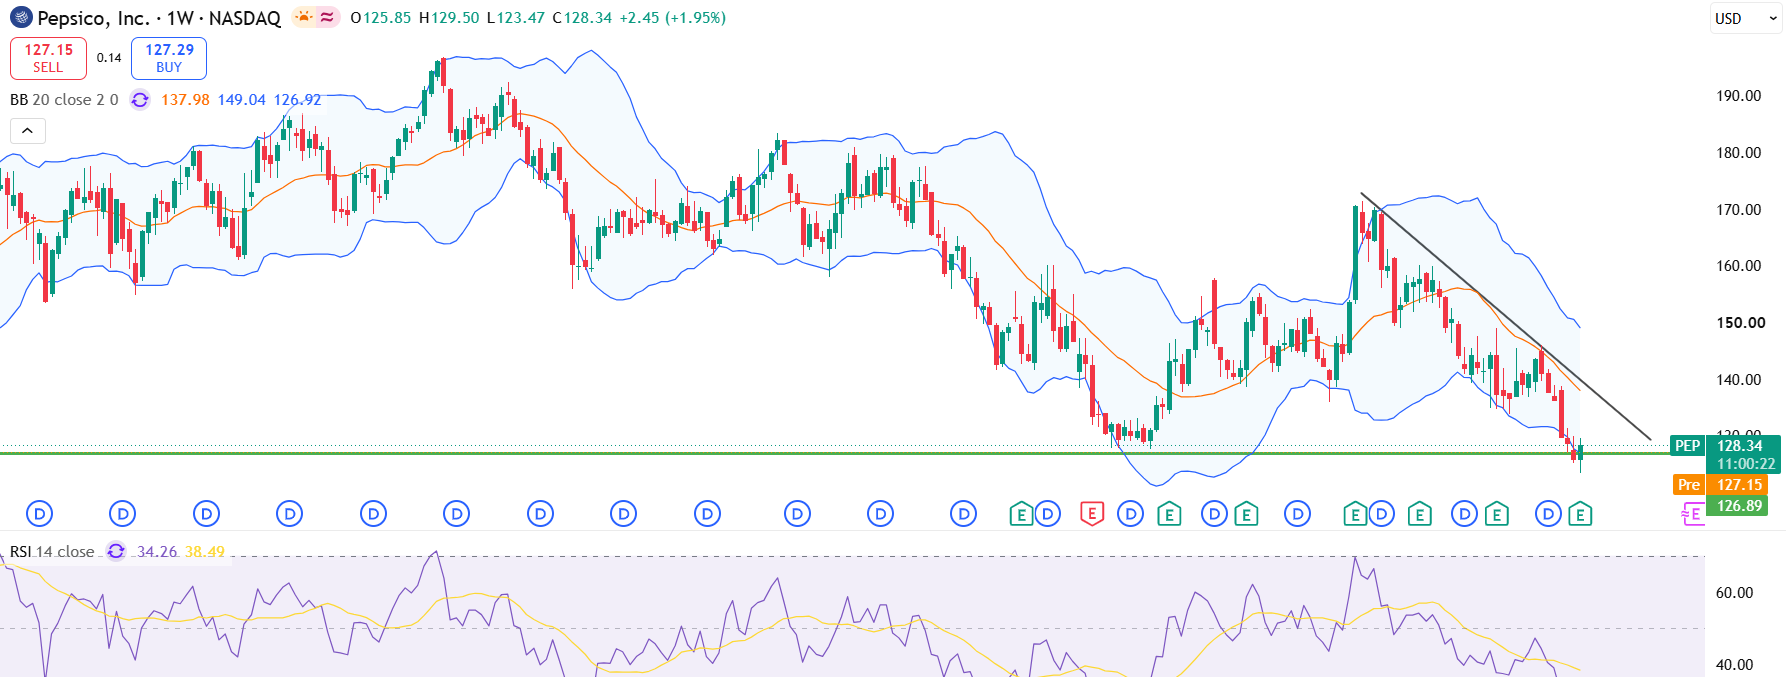
The next key resistance zone is $129.62–$131.58. A sustained move above that range would strengthen the case for a broader recovery. Until then, the rally remains an early rebound within a downtrend.
What the rebound means for investors
Thursday’s gain reflects a positive initial response to the results, but a single session does not establish a sustained recovery.
The quarter reinforced the case for PepsiCo’s revenue resilience, particularly internationally. The lower earnings forecast and continued margin pressure, however, leave the profitability recovery less certain.
Investors will be watching for stronger organic growth in North America, improving margins and evidence that additional savings can translate into more consistent earnings growth.
Warning! This material is not intended as investment advice. Past performance data does not guarantee future returns. Investing in foreign currencies may affect your returns due to their fluctuations. Any transaction in securities may result in both profits and losses. The assumptions and expectations set forth in this material are only estimates that may not be accurate and may change depending on current economic conditions. These statements do not guarantee future returns.

Meet Syam KP, a financial markets professional with more than fourteen years of experience in forex, CFDs and capital markets. Since 2012, he has worked with several brokerage firms as a trader and market strategist, developing a practical understanding of how markets move. He also holds a qualification from CISI in the United Kingdom.
At FX Junction, Syam turns complex market information into clear and useful insights. His work combines technical and fundamental analysis, portfolio management, risk management and timely commentary on global developments. Whether markets are calm or moving fast, Syam focuses on what matters most: understanding the bigger picture, spotting meaningful opportunities and keeping risk firmly in view.
Related Articles
Anthropic's Record $81 Billion IPO Loses Momentum After 34% Opening Surge
Anthropic shares surge during their Nasdaq debut before surrendering much of their early gains. Despite completing the largest initial public offering on record, the company's volatile first trading session raises questions about whether investor enthusiasm can sustain valuations amid rising AI infrastructure costs.
Read More →Australian Dollar Hits 10-Month Low as Unemployment Rises to 4.9%
The Australian dollar falls sharply after unemployment reaches its highest level in five years. With employment declining for a second consecutive month, investors are abandoning expectations of further interest-rate increases and increasingly pricing in cuts for 2027.
Read More →